Education
Sep 2025 to May 2027
New York University
Master of Science in Financial Engineering, Tandon School of Engineering, New York, NY
- MS thesis in progress (see Thesis), advised by Prof. David Shimko
Selected coursework
- Econometrics and Time Series Analysis
- Derivative Securities
- Algorithmic Trading and High-Frequency Finance
- Credit Risk and Financial Risk Management
- Model Risk Management
- Valuation for Financial Engineering
- Corporate Valuation
- Quantitative Methods in Finance
In progress, Fall 2026
- Volatility Models
- Fixed Income Quantitative Trading
- Financial Risk Management
- Real-Time Risk Management
- Financial Economics
- Advanced Topics in Financial Technology
2021 to 2025
SRM University-AP
Bachelor of Technology, Computer Science and Engineering (Artificial Intelligence and Machine Learning), Amaravati, India
- 100% merit scholarship
Selected coursework
- Linear Algebra
- Multivariable Calculus
- Differential Equations
- Probability and Statistics
- Design and Analysis of Algorithms
- Machine Learning
- Operating Systems
- Compiler Design
Thesis
The U.S. Sovereign Debt Doom Loop: A Point-in-Time Framework for Identification, Market Pricing, and Policy Response
MS thesis, New York University. Advisor: Prof. David Shimko. In progress, expected May 2027.
Research
- Too Big to Co-Move: Concentration and Sector Connectedness Around the World
SSRN preprint 6475898, October 2026. Not peer reviewed. - RateWalk: Forecasting Fed Rate Decisions with a Shrunk Markov Chain
Working paper, July 2026. Not peer reviewed. - Calm Months, Crash Months: Why Volatility Management Pays for Momentum and Not the Market
SSRN preprint 7113079, September 2026. Not peer reviewed. - VolEdge: Measuring and Trading the Variance Risk Premium with Model-Free Risk-Neutral Moments
Working paper, July 2026. Not peer reviewed. - Multi-Scale Regime Detection with Fuzzy Aggregation for Adaptive Sector Portfolio Management
SSRN preprint 6484679, July 2026. Not peer reviewed.
Projects
- ChronoFund: Point-in-Time Fundamentals Engine
Point-in-time data engine - Regime-Aware Fundamental Factor Strategy
Fundamental equity backtest - PinSight: 0DTE Options Engine and No-Lookahead Paper Trader
Options engine - DriftEdge: Prediction-Market Engine
Prediction markets
Experience
Jun 2026 to present
Course Assistant, Valuation for Financial Engineering (Prof. David Shimko)
Sep 2026 to present
Contributor, Valuation Principles, Prof. Shimko's graduate valuation textbook (Wiley, in preparation)
Jun 2026 to present
New York University, New York, NY
- Picked by the professor to lead the course's four assistants across two sections; resolve modeling questions on mortgage-pool prepayment and default, level-payment amortization, and Treasury curve bootstrapping, and flag ambiguous project specifications for revision.
- Restructured the book's Monte Carlo and variance-reduction material, built its figures, companion Python notebooks, and five Excel models, reconciled the 164-page solutions manual, and proposed additions the author approved into the text; the chapters are the course's text.
Jun 2023 to Aug 2023
Summer Intern, Framework Development
IUDX (India Urban Data Exchange), Bengaluru, India
- Built a consent-capture tool for the Agricultural Data Exchange (ADeX) in a four-person team, used to build 38 government datasets: purpose-coded, expiring consent records with RSA/SHA-256 digital-signature support for regulated data sharing.
2022 to 2023
Student Council, PR Convener
SRM University-AP, Amaravati, India
- Primary student liaison to the administration; directed cross-functional teams running the university's cultural festivals.
Skills
- Programming
- Python (pandas, NumPy, SciPy, statsmodels, scikit-learn, arch, hmmlearn), SQL, R, C++ (coursework); FastAPI, React, pytest, Git, LaTeX
- Econometrics
- VAR and TVP-VAR, Diebold-Yilmaz connectedness, Granger causality with FDR control, robust inference, panel fixed effects, Newey-West and Driscoll-Kraay errors, GARCH
- Probability and ML
- Markov chains, hidden Markov models, empirical Bayes and Dirichlet shrinkage, Kalman filtering, Monte Carlo and variance reduction, Gaussian mixtures
- Derivatives and risk
- Black-Scholes and Greeks, model-free risk-neutral moments, risk-neutral densities, variance risk premium, factor models, VaR and CVaR, stress testing
- Data
- SEC EDGAR and XBRL, FRED and ALFRED vintages, Treasury Fiscal Data, Kenneth French library, Bloomberg Terminal, WRDS
Certifications
 ARPM Quant Bootcamp (Advanced Risk and Portfolio Management)2026
 Akuna Capital Options 1012026
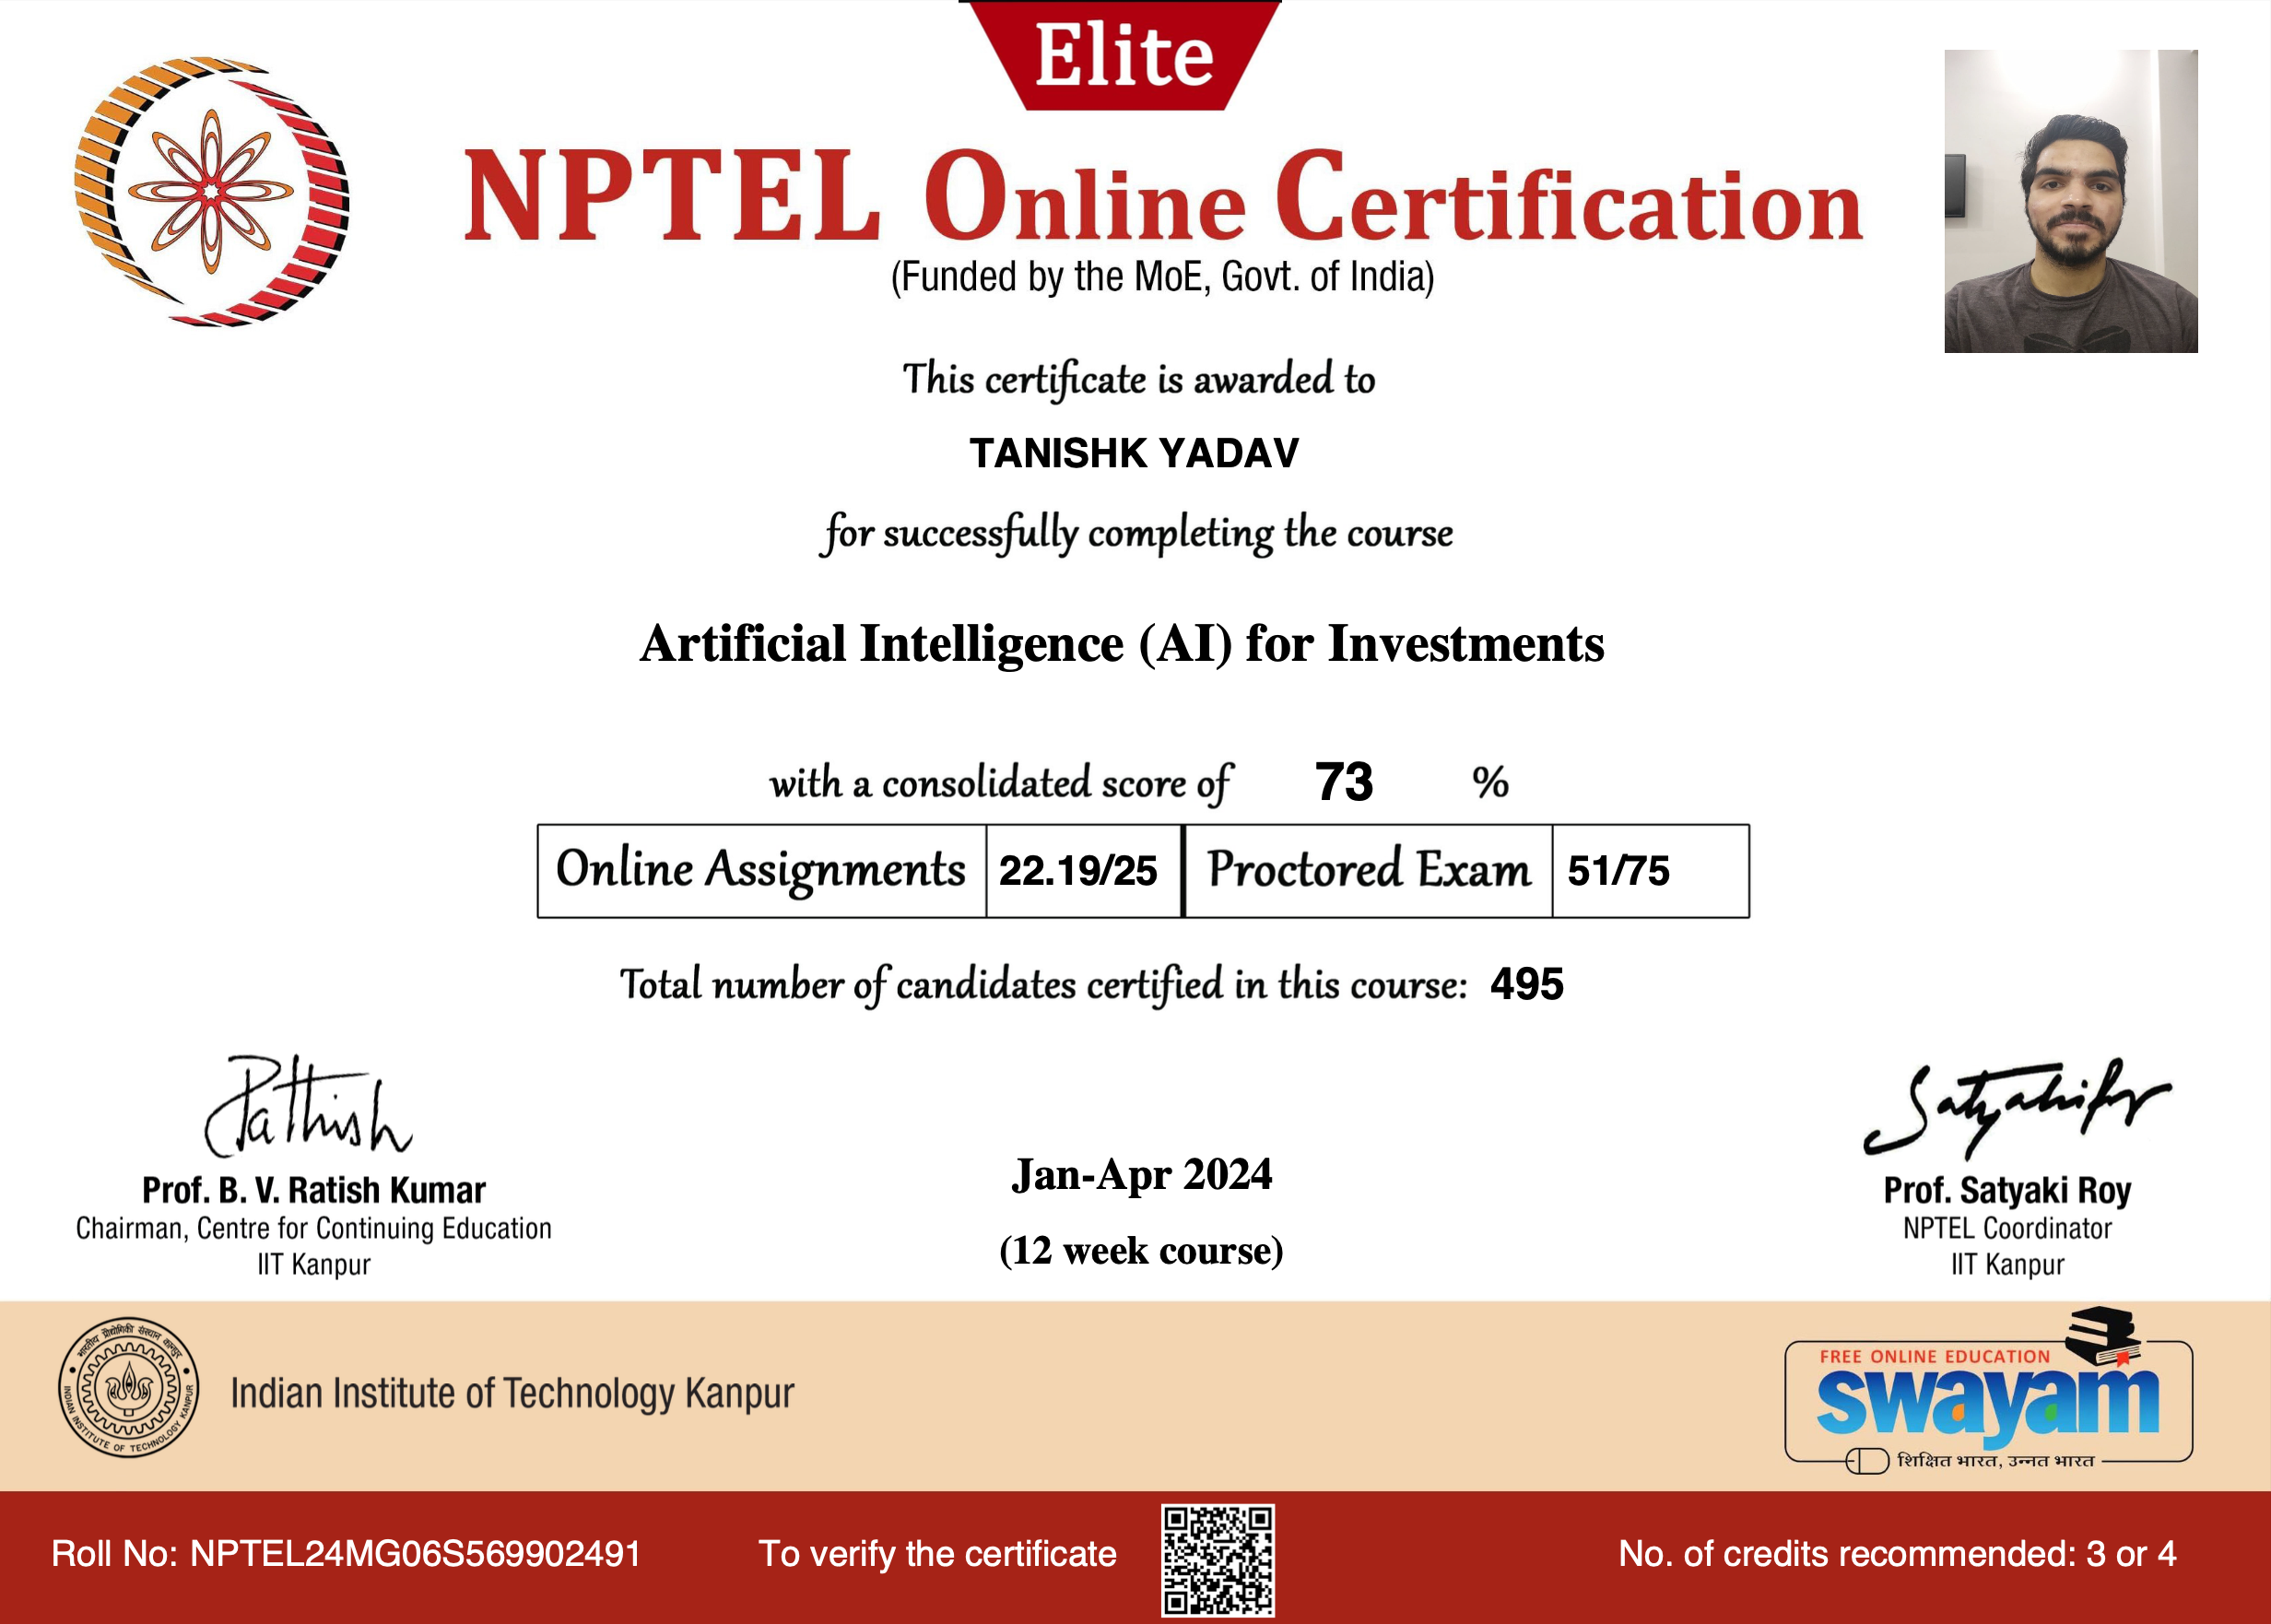 AI for Investments, NPTEL online certificationCredited toward the B.Tech
 Bloomberg Market Concepts
 Bloomberg Finance Fundamentals
 Financial Markets, Yale University (with honors)
 IBM Machine Learning Professional Certificate
Contact
Hiring for quantitative research in 2027?
I am graduating in May 2027 and looking for full-time quantitative research roles. The fastest way to reach me is email.