LinkedInJuly 20265 min read
A Markov chain over Fed policy moves and CPI regimes, walk-forward validated on first-release inflation data. Naive regime conditioning overfits; shrinkage recovers a small edge that replicates across the US, UK and Germany.
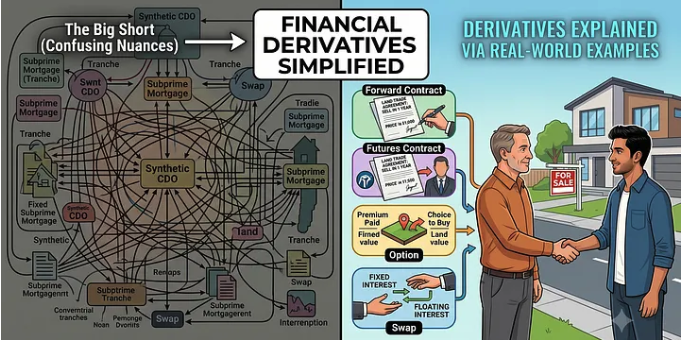
MediumMay 20268 min read
A plain-English primer on forwards, futures, options and swaps, with the everyday deals they come from.
LinkedInApril 20266 min read
The 11 sector ETFs run through Fama-French three-factor, Carhart and five-factor models: technology's returns are 92-93% explained by factors, and a simple sector-momentum rule does not beat SPY risk-adjusted.
LinkedInApril 20268 min read
The first version of the S&P 500 sector project: concentration measures, clustering, and lead-lag tests across 68 sub-sectors.
Correction: this post's Granger and clustering results did not survive later testing. The project was rebuilt as Too Big to Co-Move, which lists every retracted claim.